Renters Insurance and Home Inventory: How Apartment Dwellers Can Protect Their Belongings Before a Disaster
This post may contain affiliate links, full disclosure here.
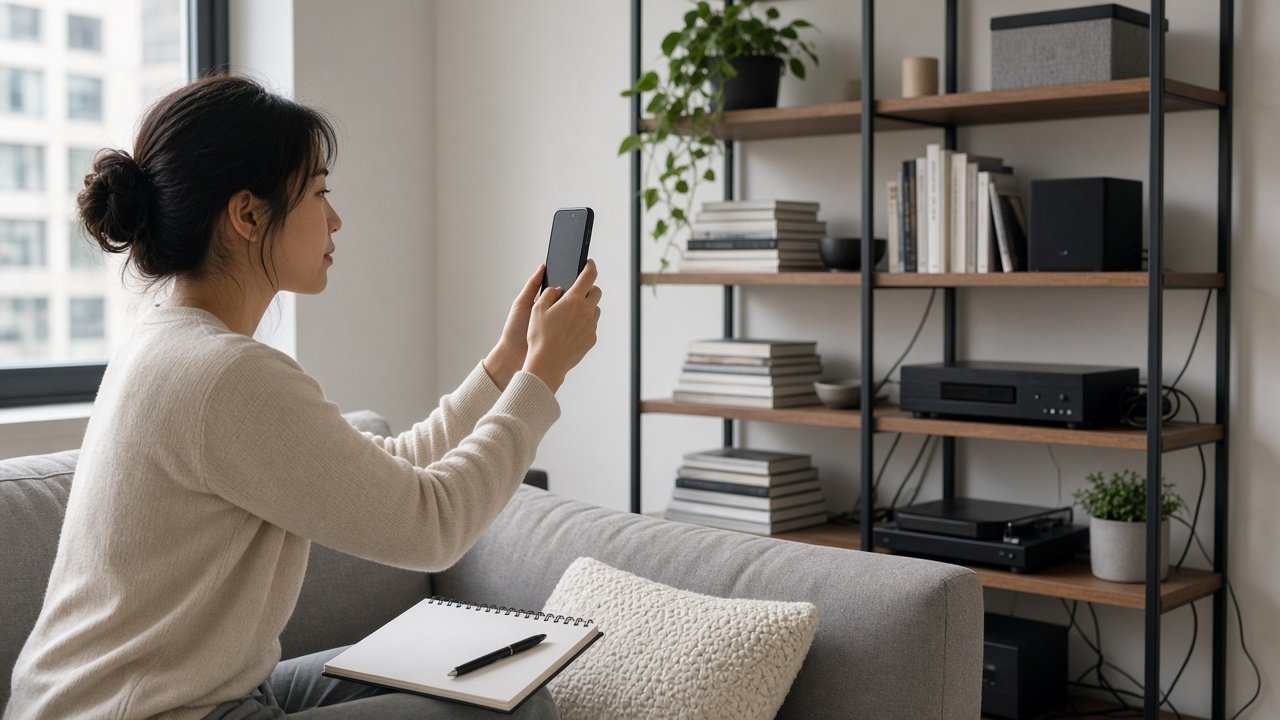
Quick answer: your landlord’s insurance covers the building, not your belongings or your hotel bill if you are displaced. A standard renters policy typically covers your possessions against fire, smoke, theft, windstorm, certain water damage and other listed perils, plus liability and additional living expenses, according to the Insurance Information Institute (Triple-I). Flood and earthquake damage are not covered and need separate policies; the National Flood Insurance Program sells contents-only flood policies to renters for up to $100,000, generally with a 30-day waiting period. Before anything happens, record a home inventory with photos or video and store a copy outside your apartment.
Preparedness is usually about water, food and power. Financial preparedness belongs on the list too. After an apartment fire, a burst pipe from the unit upstairs or a burglary, the people who recover fastest are often the ones who already had coverage and records.
This guide explains what renters insurance does and does not cover, where the common gaps are for city dwellers, and how to build a home inventory in an afternoon. It is part of our apartment emergency kit guide, which covers the physical supplies every apartment should have.
Sources: Insurance Information Institute (Triple-I), Renters Insurance consumer guide; FEMA National Flood Insurance Program (FloodSmart.gov), Flood Insurance for Renters and Buy a Policy pages; Ready.gov, Financial Preparedness and the Emergency Financial First Aid Kit. General information, not insurance or legal advice; check your own policy and state rules. Checked October 2026.
Why the Landlord's Policy Does Not Protect You
Triple-I puts it plainly: your landlord may have insurance to protect the building, but that policy will not replace your personal possessions or pay your living expenses while the building is repaired. If a fire starts two floors down and smoke ruins your furniture, clothes and electronics, the landlord’s coverage is generally not going to pay for them.
Renters insurance fills that gap. It is usually far less expensive than homeowners insurance because it does not cover the structure.
What Renters Insurance Typically Covers
Triple-I describes three basic types of protection in a standard renters policy.
Personal possessions
Your belongings are covered against damage from perils listed in the policy, which commonly include fire, smoke, lightning, vandalism, theft, explosion, windstorm and certain kinds of water damage. That includes furniture, clothing, electronics, appliances, kitchen items and even towels and bedding.
Most policies also include off-premises coverage, so items stolen from your car or a storage unit may be covered, though usually with a lower limit. Triple-I gives the example of off-premises coverage being limited to 10% of your total possessions coverage on some policies.
Liability
Liability coverage protects you if you or a family member accidentally injure someone or damage their property, including damage caused by your pets. It pays legal defense costs and court awards up to the policy limit. According to Triple-I, liability limits generally start at about $100,000. Policies also typically include no-fault medical payments coverage for guests injured in your home.
Additional living expenses (ALE)
If a covered disaster makes your apartment unlivable, ALE pays the extra cost of living elsewhere, such as hotel bills, temporary rentals and restaurant meals, above your normal expenses. In a city where a building fire can displace dozens of households for weeks, this coverage is often the most valuable part of the policy.
What Renters Insurance Does Not Cover
The exclusions matter as much as the coverage. Common gaps include:
- Floods. Triple-I notes that standard renters policies do not cover flood damage. Supplemental coverage is available.
- Earthquakes. These need a separate policy or an endorsement.
- High-value items above sublimits. Triple-I says jewelry and similar valuables are often limited to about $1,500 for theft and some other losses unless you add a floater or endorsement.
- Vehicles. Cars, vans and motorcycles need auto insurance.
- Damage you cause to your own things, such as your own pet destroying your own rug.
Always read your policy’s list of covered perils and exclusions. The specific wording controls what is paid.
Flood Insurance for Renters
Flooding is one of the most common and costly disasters, and city apartments are not immune, especially basement and ground-floor units. FEMA’s National Flood Insurance Program (NFIP) offers contents-only policies for renters in participating communities, covering up to $100,000 of belongings such as furniture, clothing, electronics, rugs and appliances.
Two things to know:
- Waiting period. NFIP coverage generally starts 30 days after purchase, with limited exceptions. You cannot wait until a storm is forecast.
- Basement limits. NFIP policies limit coverage for contents in basements, so check what is covered if you live below ground level.
NFIP contents policies do not pay additional living expenses. Some private flood insurers offer different terms. Our guide to flood safety and preparation covers the physical steps to take.
Actual Cash Value vs. Replacement Cost
Renters policies come in two main types, according to Triple-I:
| Policy type | How claims are paid | Tradeoff |
|---|---|---|
| Actual cash value | Cost to replace your items minus depreciation for age and wear | Lower premium, but older items pay out far less than a new replacement |
| Replacement cost | Cost to replace items with new ones of similar kind and quality, without depreciation | Triple-I estimates it costs about 10% more, but payouts are much closer to what you need |
If a five-year-old laptop and couch are destroyed, actual cash value may pay only a fraction of what new ones cost. For most renters rebuilding after a disaster, replacement cost is worth considering.
How Much Coverage Do You Need?
Triple-I recommends having enough coverage to replace everything you own if your home were destroyed. Most people underestimate this until they count it up, which is where a home inventory comes in. Try a quick rough tally by room: the bedroom (bed, dresser, linens, clothing, shoes), the living room (sofa, TV, electronics, rugs, books), the kitchen (small appliances, cookware, dishes, pantry food) and anything in storage. Many renters find the total is several times what they guessed.
For liability, think about your savings and income. Higher limits cost relatively little, and umbrella policies can add more. For ALE, check whether the policy uses a dollar limit or a time limit, and consider how much a few months of short-term housing would cost in your city.
How to Build a Home Inventory
A home inventory is a list of your belongings with descriptions and estimated values. Triple-I calls it the easiest way to figure out how much insurance you need, and it makes claims faster and easier. You do not need to finish it in one day.
- Start with a video walk-through. Record every room, opening closets, drawers and cabinets. Narrate brand names, models and approximate ages as you go.
- Photograph valuable items closely, including serial numbers on electronics and appliances.
- List items room by room in a spreadsheet or inventory app, with description, quantity, purchase date and estimated value.
- Save receipts and appraisals for big-ticket items, including digital receipts from email.
- Note special items, such as jewelry, art, collectibles and instruments, which may need extra coverage.
- Include the ordinary stuff. Kitchenware, linens, shoes and clothing add up quickly and are easy to forget.
- Update the inventory once a year and after major purchases. A good reminder is to review it when your policy renews, so coverage limits keep pace with what you own.
Store the Inventory Where a Disaster Cannot Reach It
An inventory saved only on a laptop in your apartment can burn with the apartment. Keep at least one copy elsewhere:
- In a cloud storage account.
- Emailed to yourself.
- On a flash drive in your go-bag or with a trusted relative.
Treat it like your other critical records. Our guide to gathering and protecting emergency documents covers how to store policy numbers, IDs and financial records the same way.
What to Do After a Loss
Triple-I’s claims guidance for renters includes these steps:
- Report crimes to the police and get a copy of the report for theft or vandalism.
- Call your insurer or agent quickly and ask about claim deadlines, coverage and deductibles.
- Do not throw out damaged items until an adjuster has seen them, unless they are a health hazard; photograph or video everything first.
- Prepare a list of damaged or stolen items using your inventory and receipts.
- Keep receipts for relocation expenses if you have to live elsewhere.
- Return claim forms promptly.
If you are unhappy with how a claim is handled, Triple-I suggests talking to your agent or the company’s claims manager first, then contacting your state insurance department.
Financial Preparedness Beyond Insurance
Insurance pays after the fact, often weeks later. Ready.gov’s financial preparedness guidance encourages households to plan for the gap, too. A few steps help renters bridge it:
- Keep some cash at home. Ready.gov notes that ATMs and card readers may not work during a power outage or disaster. Small bills are easiest to use.
- Build an emergency fund for deductibles, a security deposit on temporary housing and immediate needs before ALE payments arrive.
- Fill out an Emergency Financial First Aid Kit (EFFAK). Ready.gov offers this free checklist and workbook to help households gather key financial, insurance and household information in one place.
- Know your lease. Check what it says about rent if the unit becomes uninhabitable and how to notify your landlord after damage.
- List your policy details (insurer, policy number, claims phone number) in your phone and in your printed emergency documents.
City-Specific Risks to Ask About
Apartment life comes with risks that are worth raising when you buy or review a policy:
- Water damage from other units. Ask how your policy handles sudden water damage from a neighbor’s leak or burst pipe.
- Sewer or drain backup. Often excluded unless you add an endorsement, which matters for ground-floor and basement units.
- Fire in another unit. Smoke and water damage from firefighting can affect many apartments at once. Our apartment fire safety plan covers prevention and escape.
- Theft from shared spaces, such as package rooms, bike rooms and storage cages.
- Roommates. Triple-I notes that a roommate or partner is usually not automatically covered unless named, depending on state rules and the insurer.
Saving on Renters Insurance
Triple-I suggests several ways to lower premiums: choose a higher deductible you can afford, bundle with an auto or other policy, and ask about discounts for smoke detectors, deadbolts or security systems. Get at least three quotes, and do not shop on price alone. Claims service matters most when you actually need the policy.
Frequently Asked Questions
Frequently Asked Questions
Does my landlord's insurance cover my belongings? Generally no. A landlord's policy covers the building. Your possessions and temporary living costs need your own renters policy.
Does renters insurance cover flooding? Standard renters policies do not cover floods. Renters can buy contents-only flood insurance from the NFIP, up to $100,000, typically with a 30-day waiting period, or from some private insurers.
Does renters insurance pay for a hotel if I am displaced? Usually yes, through additional living expenses coverage, when the damage is caused by a covered peril. Check your policy's dollar or time limits.
What is the best way to make a home inventory? Record a video of every room, photograph valuables and serial numbers, list items with estimated values and keep copies of receipts. Store a copy in the cloud or outside your home.
Are expensive items fully covered? Often not. Triple-I notes valuables like jewelry may be limited to around $1,500 for some losses unless you add a floater or endorsement.
Is replacement cost coverage worth it? Replacement cost pays to buy new items without deducting depreciation. Triple-I estimates it costs about 10% more than actual cash value coverage.

The Bottom Line
Renters insurance is one of the least expensive pieces of disaster preparedness for apartment dwellers, and a home inventory makes it work when you need it. Know what your policy covers, close gaps like flood and valuables, record your belongings with video and photos, and store that record somewhere a disaster cannot reach. Then add your policy number to your emergency documents so it is ready on the worst day.